
The term carries two meanings, and readers usually arrive looking for one and needing the other. Bodily injury refers to any physical harm someone suffers in a crash, whether it is visible like a broken leg or a laceration, or not visible like a concussion or a traumatic brain injury.
On an insurance policy, the phrase means something narrower. Ask what is bodily injury liability and you are asking about a coverage type, one that responds when the policyholder is the person at fault. In Florida the subject gets an extra layer of confusion, because the state built its auto insurance system around a coverage that has nothing to do with fault at all.
What Does Bodily Injury Liability Coverage Actually Pay For?
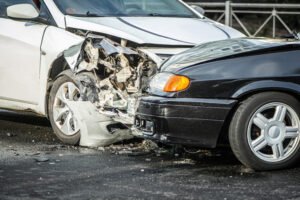
Bodily injury liability coverage pays other people when you cause a crash that hurts them. It covers their medical treatment, lost income, and pain and suffering up to your policy limits, and pays nothing toward your own injuries or your own vehicle.
Florida does not require this coverage on an ordinary private passenger car, which is why so many crashes here involve a driver with no bodily injury coverage at all.
To consult with an experienced personal injury lawyer today
(855) 780-9986
Key Takeaways About Bodily Injury and Bodily Injury Liability
- As a medical term, bodily injury is any physical harm a person suffers through someone else’s negligence or through an accident.
- As an insurance term, bodily injury liability protects other people from your negligence. It never pays your own medical bills.
- Florida requires $10,000 in personal injury protection and $10,000 in property damage liability for a private passenger vehicle, and does not require bodily injury liability coverage.
- The $10,000 and $20,000 bodily injury figures many drivers have heard come from the state’s proof of financial responsibility rules, which apply after certain events rather than at registration.
- When an at fault driver’s limits fall short of the harm caused, the gap is usually filled by the injured person’s own uninsured or underinsured motorist coverage, or by nothing at all.
Key Figures Behind Florida’s Coverage Rules
Every number below comes from the statute rather than from an insurance company’s marketing material.
| What it covers | Required amount | Source |
|---|---|---|
| Personal injury protection on a private passenger vehicle | $10,000 in medical and disability benefits, $5,000 in death benefits | § 627.736(1) |
| Property damage liability | $10,000 | § 324.022(1) |
| Bodily injury liability on an ordinary private passenger car | Not required by any Florida statute; § 627.733 sets out what is required, and it is not this | Not applicable |
| Bodily injury figures under proof of financial responsibility | $10,000 per person, $20,000 per crash | § 324.021(7) |
 That third row changes how a Florida crash plays out. A driver can be entirely lawful and still have zero dollars available to compensate someone they seriously injured.
What Is Bodily Injury Liability Insurance?
It is the coverage that pays a person you hurt, on your behalf, when you are legally responsible for a crash. It also funds your legal defense if that person sues you.
The clearest way to hold the idea is to compare it to the coverage sitting right next to it on the same policy.
| Bodily injury liability | Property damage liability | |
|---|---|---|
| Who it pays | People you injure | People whose property you damage |
| What it covers | Medical care, lost income, pain and suffering | Vehicle repair or replacement, other damaged property |
| Whose losses | Theirs, never yours | Theirs, never yours |
| Required in Florida for a private passenger car | No | Yes, $10,000 |
Limits are usually written as two numbers, such as 25/50. The first is the most the policy pays for any one injured person. The second is the most it pays for everyone injured in a single crash, no matter how many people that is.
That second number is where serious crashes come apart. A policy with a $50,000 per crash limit splits that amount among every injured claimant, which can leave each person with a fraction of what their treatment cost.
Is Bodily Injury Coverage Required in Florida?
No, not for an ordinary private passenger car. This is the point most often stated incorrectly, including on other law firm websites, so it is worth being precise about.
Section 627.733, Florida Statutes requires security in the form of personal injury protection under the no fault law. Section 324.022(1) requires the ability to respond in damages for property damage in the amount of $10,000. Neither imposes a bodily injury liability requirement.
When Does the State Require Bodily Injury Coverage?
After certain triggering events. The $10,000 per person and $20,000 per crash figures live in section 324.021(7), Florida Statutes, which defines proof of financial responsibility. Those obligations attach following events such as a qualifying crash, a conviction, or a license revocation, and separate rules apply to for hire vehicles.
Put simply, Florida asks a driver to carry bodily injury coverage after they have already given the state a reason to worry, rather than before.
Coverage is available to buy at any time, and in a state without a mandate it is the single most useful optional coverage a driver can add for other people’s protection. Uninsured motorist coverage is the one that protects the driver’s own household.
Click to contact our Florida Attorneys today
Who Pays Your Medical Bills If Bodily Injury Coverage Is Not Involved?
Your own personal injury protection pays first, regardless of who caused the crash. That is the practical answer for most Florida crash victims, and it is why the at fault driver’s coverage often does not enter the picture for months.
Section 627.736(1)(a), Florida Statutes provides 80 percent of reasonable medical expenses and 60 percent of lost gross income, subject to a $10,000 cap that depends on a qualifying provider determining an emergency medical condition, or $2,500 where one is not determined. Benefits also require initial services and care within 14 days of the crash.
 Personal injury protection pays nothing for pain and suffering. That category becomes available only in a liability claim against the at fault driver, and only once the injury clears a standard the statute sets out.
What Makes an Injury Serious Enough to Sue the Other Driver?
Florida sets that standard in section 627.737(2), Florida Statutes. To recover for pain, suffering, mental anguish, and inconvenience, the injury has to consist in whole or in part of one of four things:
- Significant and permanent loss of an important bodily function
- Permanent injury within a reasonable degree of medical probability, other than scarring or disfigurement
- Significant and permanent scarring or disfigurement
- Death
The word carrying the weight in three of those is permanent. An injury that hurts and then resolves does not clear the line, which is why carriers push so hard on the idea that treatment stopped because the claimant got better.
The threshold governs those noneconomic damages only. Economic losses above what PIP paid are pursued against the at fault driver without it.
Once a claim crosses that line, the at fault driver’s bodily injury limits are what stands between you and the rest of your losses. That is where the number on their declarations page starts to decide the outcome.
Submit a Consultation Request form today
What Happens When the At Fault Driver’s Limits Run Out?
The claim turns to whatever other coverage exists, and for most people that means their own policy. Uninsured motorist coverage responds when the at fault driver had none. Underinsured motorist coverage responds when their limits were smaller than the damages.
Florida handles the second scenario in the definition itself. Section 627.727(3)(b), Florida Statutes treats a vehicle as uninsured where the liability insurer provided bodily injury limits “less than the total damages sustained.”
There is also a procedural step that has to happen before any settlement is signed with the at fault driver’s carrier, because skipping it can end an underinsured motorist claim worth more than the settlement.
How Is Negligence Proven in a Bodily Injury Claim?
By showing that the other driver owed a duty of care, failed to meet it, and caused your injuries as a result. Most of that work is documentary rather than argumentative.
The crash report is usually the starting point, followed by witness interviews, photographs, vehicle damage patterns, and any available video. Sometimes the at fault driver’s insurer concedes fault, in which case the dispute moves to the value of the injuries instead.
The harder part is often proving that the injuries are as significant as you and your doctor believe they are. That takes consistent treatment records, imaging where it applies, and a clear account of what changed in your daily life. Gaps in treatment are the single most common thing carriers use to discount a claim.
 Shared fault comes up as well. Section 768.81(6), Florida Statutes bars recovery entirely for a party found more than 50 percent at fault for their own harm, and reduces it proportionally below that line.
When Should You Talk to a Lawyer About a Bodily Injury Claim?
When the injuries are serious, when the coverage is unclear, when fault is disputed, or when an offer has been made that you cannot evaluate. Those are the four situations where the outcome usually changes based on who is handling the claim.
Our role is to identify every applicable policy, follow the statutory notice steps in the right order, and value the claim against the medical record rather than against an adjuster’s software. In many cases people find the coverage picture is broader than they assumed, particularly where a household holds more than one policy.
Bogin, Munns & Munns handles personal injury claims on a contingency fee, and the consultation is free.
The Coverage Nobody Reads Until It Matters
Most drivers discover what their policy contains on the worst day of their year. By then the choice was made months earlier, in a quote comparison that showed only the price.
If you were hurt by a driver whose coverage does not reach your injuries, there are usually more options than the first adjuster describes. Bogin, Munns & Munns offers a free case review, and our personal injury work is handled on a contingency fee. We don’t get paid unless you win.
Call +1 (407) 578-9696 or reach us through our contact form. Our attorneys serve Central Florida from eleven offices along the I-4 corridor and the Space Coast, and we can start with a look at your Orlando car accident claim and your policy.
Call or Submit Our Consultation Request Form Today